Coverage basics
A burst pipe and a $10,000 cap: how Citizens limits water damage claims
How Citizens’ $10,000 limit on water damage from pipes and appliances works, when it applies and what to check in your policy before a claim.
By Ricardo Arevalo, Florida Public Adjuster · Published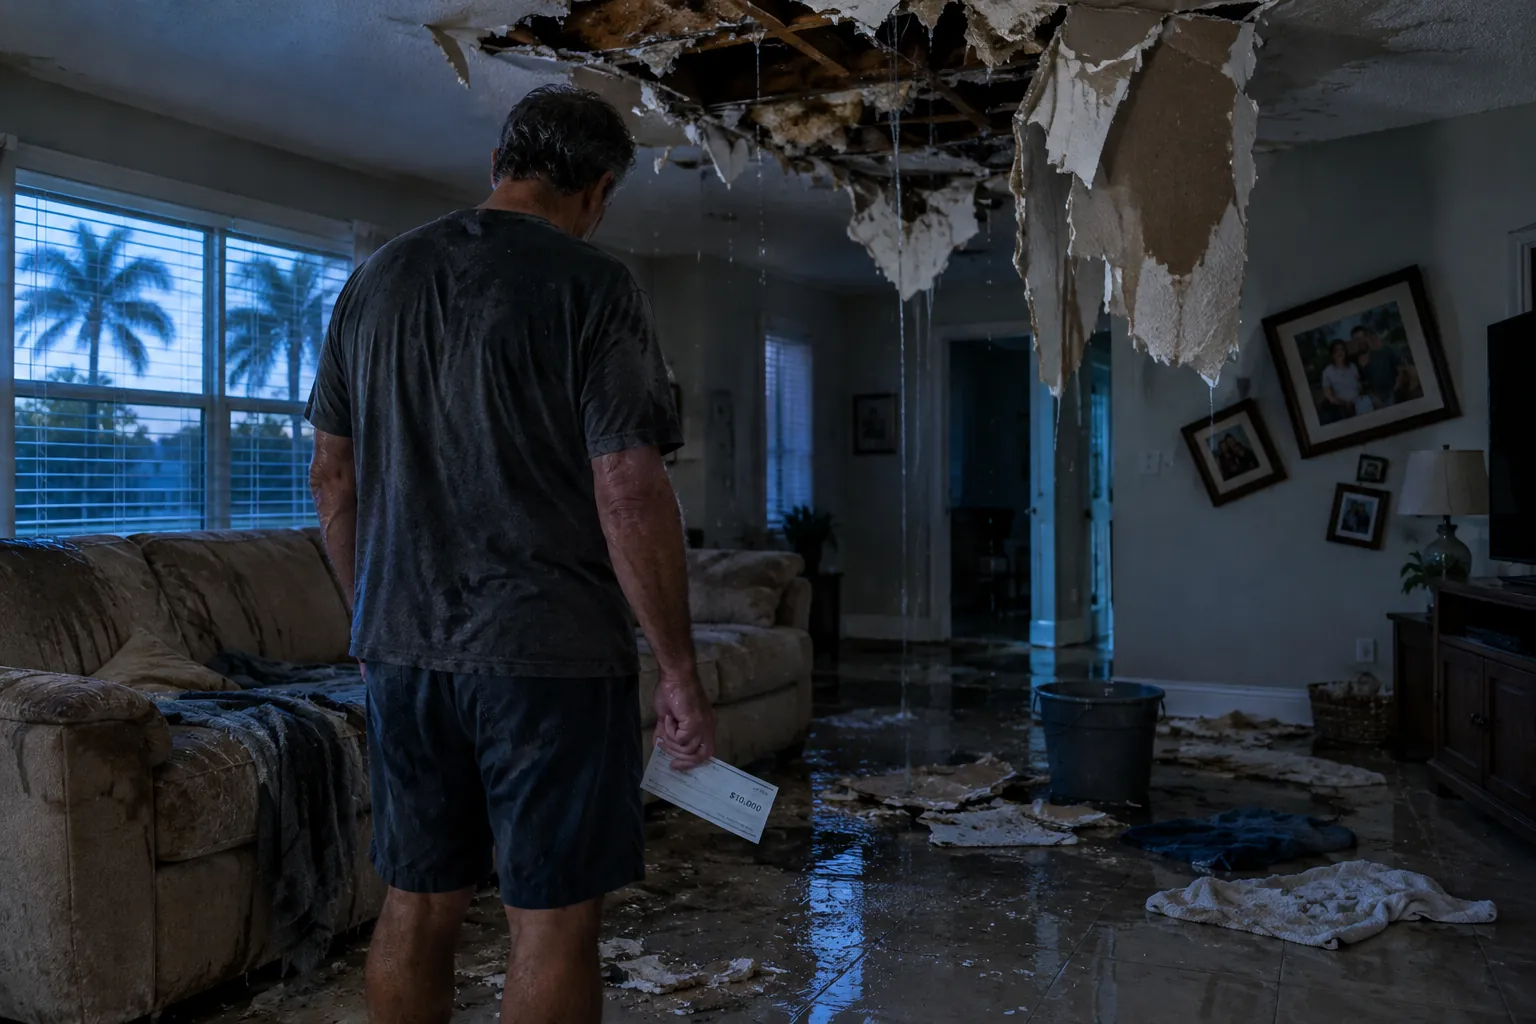
A limit for one kind of damage
When a pipe bursts or a water heater fails in a home insured by Citizens Property Insurance, the policy may pay far less than the owner expects. The reason is a $10,000 limit that the insurer created by the State of Florida has applied since 2018 to water damage that has nothing to do with the weather.
The cap does not apply in every case. It depends on who makes the repairs and which company removes the water in the first hours, according to the claim brochure Citizens published in May 2025.
The condition: Citizens’ contractors
The rule takes only a few lines. If the policyholder chooses not to use Citizens’ Managed Repair Contractor Network for covered damage from an accidental discharge of water or steam, “your policy has a $10,000 coverage limit,” the brochure says.
Those who accept the program do not face that cap. Citizens’ Board of Governors said so in April 2018, when it approved the change: policyholders who used its managed repair program would not be subject to the policy sublimits.
The first hours count too
The other detail is the water removal. Citizens offers a free emergency service, with no deductible, for eligible policies. If the owner hires another company to dry the house, that work is capped at $3,000, and what Citizens pays for it comes out of the $10,000.
In practice, a homeowner who uses an outside drying company and an outside contractor may be left with about $7,000 for permanent repairs. Citizens did that math itself in 2018, when it said those who did not take part should have “at least $7,000 available for permanent repairs” after emergency remediation.
What falls outside
Water that comes in with a hurricane or a storm is a different story: the limit refers to losses unrelated to the weather, such as a failed supply line. Nor is Citizens the only insurer that uses one. Other Florida insurers have similar endorsements, each with its own conditions, and the state’s courts have ruled differently depending on how each policy is worded.
Before calling the insurer
The brochure itself warns that when it and the policy disagree, the policy controls. That makes the declarations page and the endorsements, where water damage limits and deductibles appear, the first stop. It also helps to ask the insurer in writing which programs apply to the claim, and to keep every invoice and photo.
RicardoPA reviews policies and claims in a free evaluation.
Frequently asked questions
Does Citizens only pay $10,000 for water damage?
Not for every water claim. The $10,000 limit applies to accidental discharges of water or steam, such as a burst pipe, when the policyholder chooses not to use Citizens’ Managed Repair Contractor Network for the permanent repairs. Water damage from a hurricane or a storm is a different kind of loss.
Does the $10,000 include emergency water removal?
If you use your own mitigation company instead of Citizens’ free Emergency Water Removal Services, that service is limited to $3,000, and what Citizens pays for it reduces the $10,000 limit.
Do other insurers have the same limit?
Many Florida insurers use similar water damage endorsements, but the amount and the conditions depend on each policy. Your declarations page and endorsements show what applies.
General information only, based on Florida law at the date shown. It is not legal advice, and initial guidance does not replace an evaluation by a licensed public adjuster.