Claim services · Miami & South Florida
Roof Leak Insurance Claim Adjuster in Miami
Looking for a roof leak insurance claim adjuster in Miami? RicardoPA helps connect visible roof damage, interior leaks and the documents behind your insurance claim.
- The reported event and when signs of damage appeared
- Roof and interior observations recorded by qualified professionals
- Differences between available repair scopes and insurer estimates
Tell us about your property.
A few details to start your free evaluation. We will contact you to arrange a phone or Zoom consultation.
- Licensed public adjusterFlorida license W319359
- English and SpanishTalk in the language you prefer
- Free first evaluationBy phone, Zoom or a home visit
- South FloridaMiami-Dade, Broward and Palm Beach
Understand the details
What we review in a roof damage claim
A stain on the ceiling and damage to the roof may be parts of the same story. We begin with what you have observed and the records available, then discuss how the reported damage has been documented in your claim.
We help property owners across Miami-Dade, Broward and Palm Beach, including Miami, Doral, Hialeah, Kendall, Coral Gables and Fort Lauderdale, by phone or Zoom and with home visits by appointment.
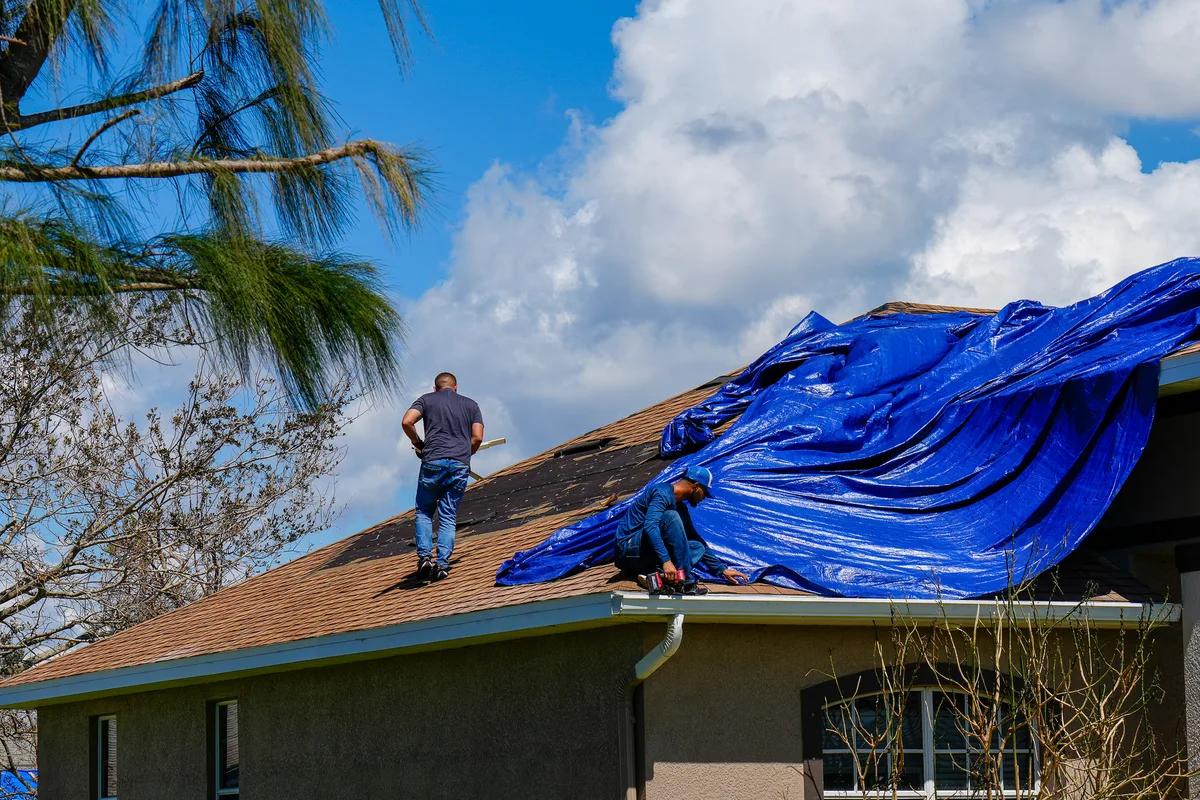
Stay clear of unstable roofing and damaged structures. Do not enter an unsafe area to document a loss.
Roof leak claims
How a roof leak insurance claim comes together
A leak inside, damage on the roof
A damp stain on the ceiling after a rain may seem minor, but roof leaks often start small and can affect the structure of the property and lead to mold growth over time. The roof and the interior are usually parts of the same claim, so the damage in each room matters as much as the roof itself.
Documenting a roof leak safely
Good roof documentation never requires climbing onto the roof yourself:
- Take photos from the ground and of any interior stains, leaks or fallen debris
- Write down the date of the storm or event and when you first noticed the damage
- Keep receipts for tarps and emergency repairs
- Ask for inspection reports and estimates in writing, including the roof age and material the insurer assumed
Florida rules that shape roof claims
The roof is often the most disputed part of a Florida property claim. Recent laws added rules on roof age, a possible separate roof deductible, which does not apply to hurricane roof losses, and how the building code applies when 25 percent or more of a roof section is repaired. Your policy, and the age and construction of your roof, decide which of these apply.
Roof claims in Florida: age, deductibles and the 25 percent rule
When more damage shows up later
Water from a roof leak can travel behind walls and under flooring. If you find more damage after the claim was adjusted, Florida allows a supplemental claim within 18 months after the date of loss.
Found more damage? How a supplemental claim works in Florida
Simple process
How it works
Tell us what happened
Complete the form or call. A few details are enough to start.
We contact you
We call you back to arrange a free consultation by phone, Zoom or at your property by appointment.
Understand your next steps
We review the information available and explain clearly what may come next with your claim.
Client experiences
What property owners say
“Super responsive to any request and messages sent.”
“… knowledgeable, professional and truly care about their clients.”
“… very helpful throughout the claim process …”
Selected excerpts from individual experiences. Results vary from claim to claim.
Questions
Roof damage claim questions in Miami
Should I climb onto the roof to take photos?
No. Share photos and reports you can obtain safely. Roof access and inspection should be left to appropriately qualified professionals.
Can you review an existing roof claim?
Yes. Bring the insurer’s estimate or decision and the documentation you have. A review does not promise a particular coverage or payment outcome.
Questions people ask
Roof leak insurance claims in Miami: what people ask
Can I make an insurance claim if my roof is leaking?
Yes. You can report a roof leak to your insurer, and in Florida notice of a new claim must be given within 1 year after the date of loss. Whether it is covered depends on the cause and the policy: policies commonly exclude wear and tear, lack of maintenance and constant or repeated leakage over 14 days or more, so the cause and the timeline matter.
What not to say to a roof insurance adjuster?
Avoid guessing where the leak came from or how long it has been there, such as saying it has been leaking for months, and avoid saying the damage does not look that bad. Do not rush to accept a settlement amount or offer repair estimates before the roof and the interior have been reviewed by a professional. Stick to facts you can show, such as the date of the storm, when you first noticed the leak and your photos.
What is the 15 year roof rule in Florida?
Section 627.7011 of the Florida Statutes says an insurer may not refuse to issue or renew a homeowners policy solely because the roof is less than 15 years old. For a roof at least 15 years old, the insurer must let you have it inspected by an authorized inspector, at your expense, and if the inspection shows at least 5 years of useful life remaining, it may not refuse to issue or renew solely because of roof age. The rule is about getting and keeping coverage; how a roof claim is paid depends on the policy.
Does homeowners insurance cover roof leaks in Florida?
It depends on the cause and the policy. Standard homeowners policies cover many wind losses but commonly exclude wear and tear, lack of maintenance and constant or repeated leakage over 14 days or more. Some policies also pay older roofs at actual cash value or include a separate roof deductible, which does not apply to hurricane roof losses.
Guides
Guides about this kind of claim
Roof claims in Florida: age, deductibles and the 25 percent rule
What Florida law says about roof age and insurance, how a separate roof deductible works, and when a partial roof repair needs more than the damaged area.
Read articleWhen the insurance adjuster comes: what to expect at the inspection
What Florida law requires of the insurer’s adjuster, how to prepare your home for the inspection, and what to ask for afterward.
Read articleAfter a storm: how to handle contractors and door-to-door offers
Florida rules on contractor solicitation and assignment of benefits, how to verify a license, and the red flags to watch for after a hurricane.
Read articleHow the hurricane deductible works in Florida
What a percentage hurricane deductible is, how to calculate yours from the declarations page, and why it applies once per calendar year in Florida.
Read article
Related claim services
Explore related claim services
Water Damage Claims
A clearer starting point for leaks, plumbing incidents and water damage to your home or business.
Explore this serviceHurricane & Storm Damage Claims
Organize the impact of a hurricane or storm on your property, one affected area at a time.
Explore this serviceFire & Smoke Damage Claims
A considered review of fire, smoke and related property damage once everyone is safe.
Explore this service
Let’s talk about your property.
Call or send your details and we will contact you to arrange your free evaluation.
Ricardo Arevalo · Florida Public Adjuster · W319359
Public adjusting firm license: W824117