Coverage basics
Roof claims in Florida: age, deductibles and the 25 percent rule
What Florida law says about roof age and insurance, how a separate roof deductible works, and when a partial roof repair needs more than the damaged area.
By Ricardo Arevalo, Florida Public Adjuster · Published
Why roofs get their own rules
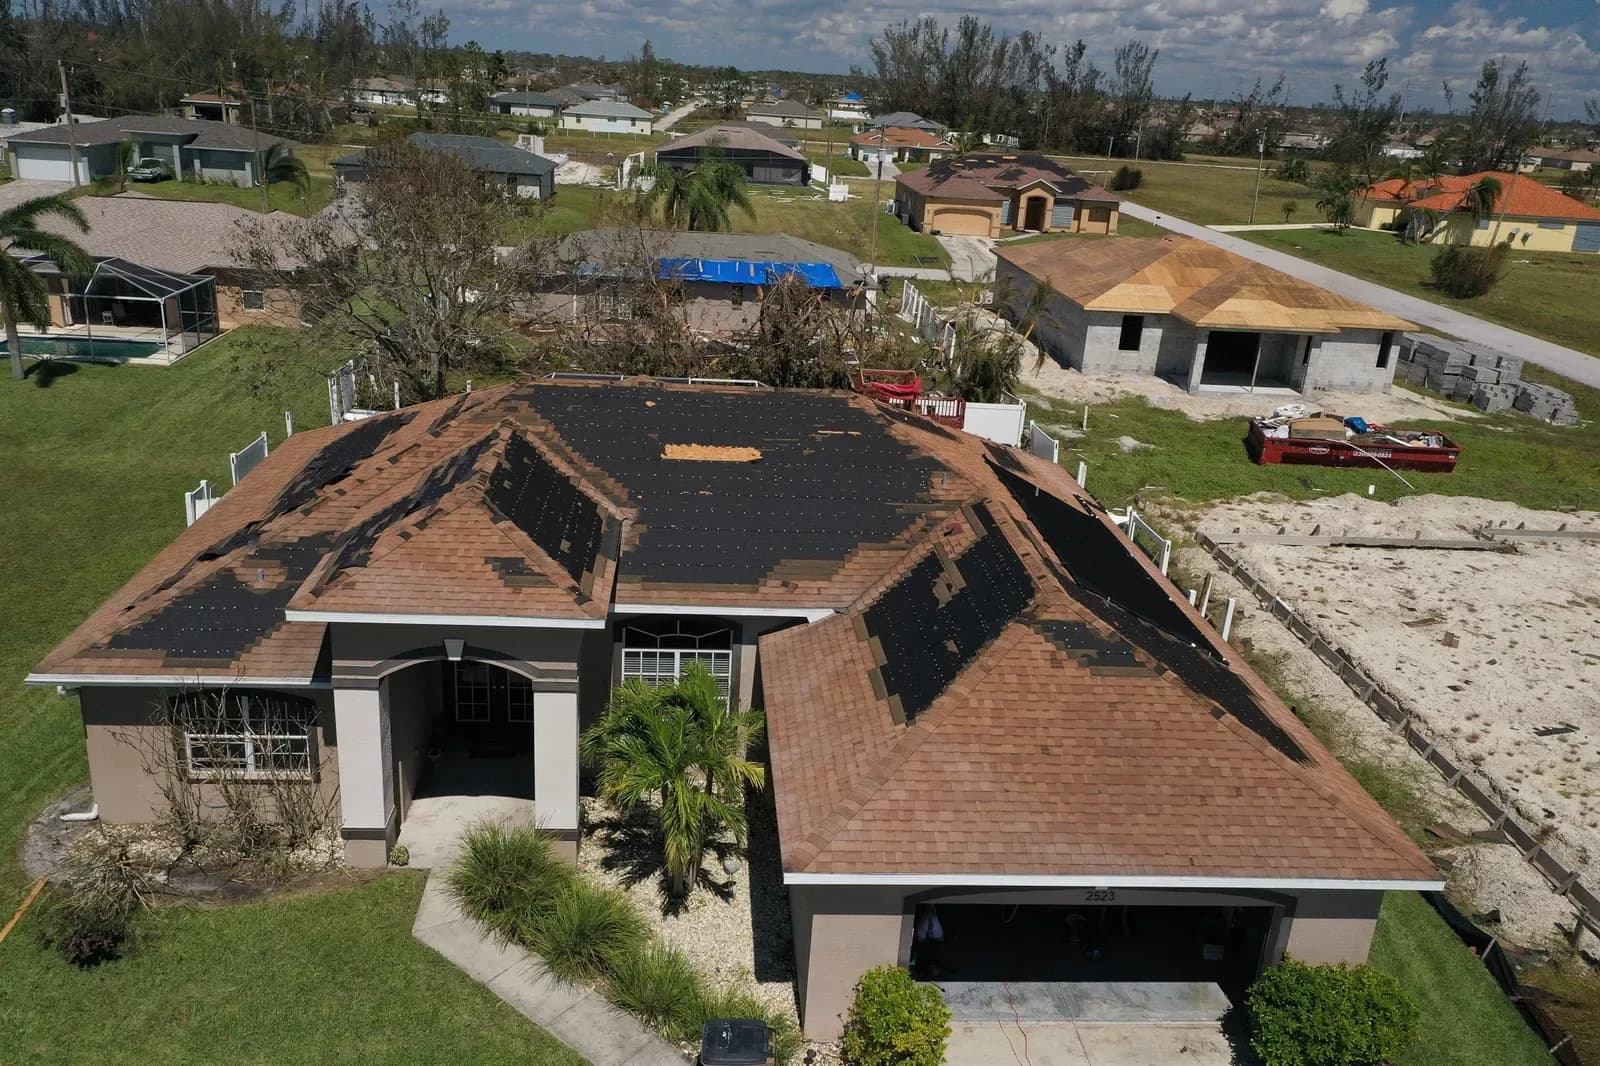
The roof is often the most disputed part of a Florida property claim. Recent laws added rules on roof age, a possible separate roof deductible and how the building code applies to partial repairs. Your policy, and the age and construction of your roof, decide which of these apply.
Roof age and your policy
Section 627.7011 of the Florida Statutes limits how insurers can use the age of a roof:
- An insurer may not refuse to issue or renew a homeowners policy solely because the roof is less than 15 years old
- For a roof at least 15 years old, the insurer must let you have it inspected by an authorized inspector, at your expense, before requiring a replacement as a condition of coverage
- If that inspection shows at least 5 years of useful life remaining, the insurer may not refuse to issue or renew solely because of roof age
These rules are about getting and keeping coverage. How a roof claim is paid depends on the policy, which may settle older roofs at actual cash value or on a payment schedule.
The separate roof deductible
Florida allows insurers to include a separate roof deductible in some residential policies. Under section 627.701, it:
- Cannot exceed the lesser of 2 percent of the dwelling (Coverage A) limit or 50 percent of the cost to replace the roof
- Applies only to claims adjusted on a replacement cost basis, and the premium must include a credit for it
- Does not apply to hurricane roof losses, a total loss of the home, a tree or other hazard that punctures the roof deck, or a repair of less than 50 percent of the roof
When the roof deductible applies, no other deductible applies to the loss from the same peril. The insurer may pay the roof at actual cash value until you show that you paid the roof deductible.
The 25 percent rule and newer roofs
Under the Florida Building Code, repairing or replacing 25 percent or more of a roof section has traditionally required bringing the whole section up to current code. Section 553.844 now makes an exception: if the roof was built, repaired or replaced under the 2007 Florida Building Code or a later edition, only the portion being repaired must meet the code in effect. For older roofs the rule can still widen the scope of a repair, and ordinance or law coverage may pay for code-required work.
Documenting a roof claim safely
Good roof documentation never requires climbing onto the roof yourself:
- Take photos from the ground and of any interior stains, leaks or fallen debris
- Write down the date of the storm or event and when you first noticed the damage
- Keep receipts for tarps and emergency repairs
- Ask for inspection reports and estimates in writing, including the roof age and material the insurer assumed
Frequently asked questions
Can my insurer drop me because my roof is old?
Not solely because the roof is less than 15 years old. For an older roof, you can have it inspected by an authorized inspector; if it shows at least 5 years of useful life, the insurer may not refuse to issue or renew solely because of its age.
Does the roof deductible apply to hurricane damage?
No. Under Florida law the separate roof deductible does not apply to roof losses caused by a hurricane; the hurricane deductible applies instead.
Will the insurer pay to replace the whole roof?
It depends on the damage, the policy, matching and code requirements. For roofs built under the 2007 Florida Building Code or later, only the repaired portion must meet current code when 25 percent or more is repaired.
General information only, based on Florida law at the date shown. It is not legal advice, and initial guidance does not replace an evaluation by a licensed public adjuster.