Florida claims
Found more damage? How a supplemental claim works in Florida
What counts as a supplemental property insurance claim in Florida, the 18-month deadline, and how to document additional damage or costs found during repairs.
By Ricardo Arevalo, Florida Public Adjuster · Published
What a supplemental claim is
Section 627.70132 of the Florida Statutes defines a supplemental claim as a claim for additional loss or damage from the same peril that the insurer has already adjusted, or for costs incurred while completing repairs or replacement under an open claim that was reported on time. In practice it covers situations like these:
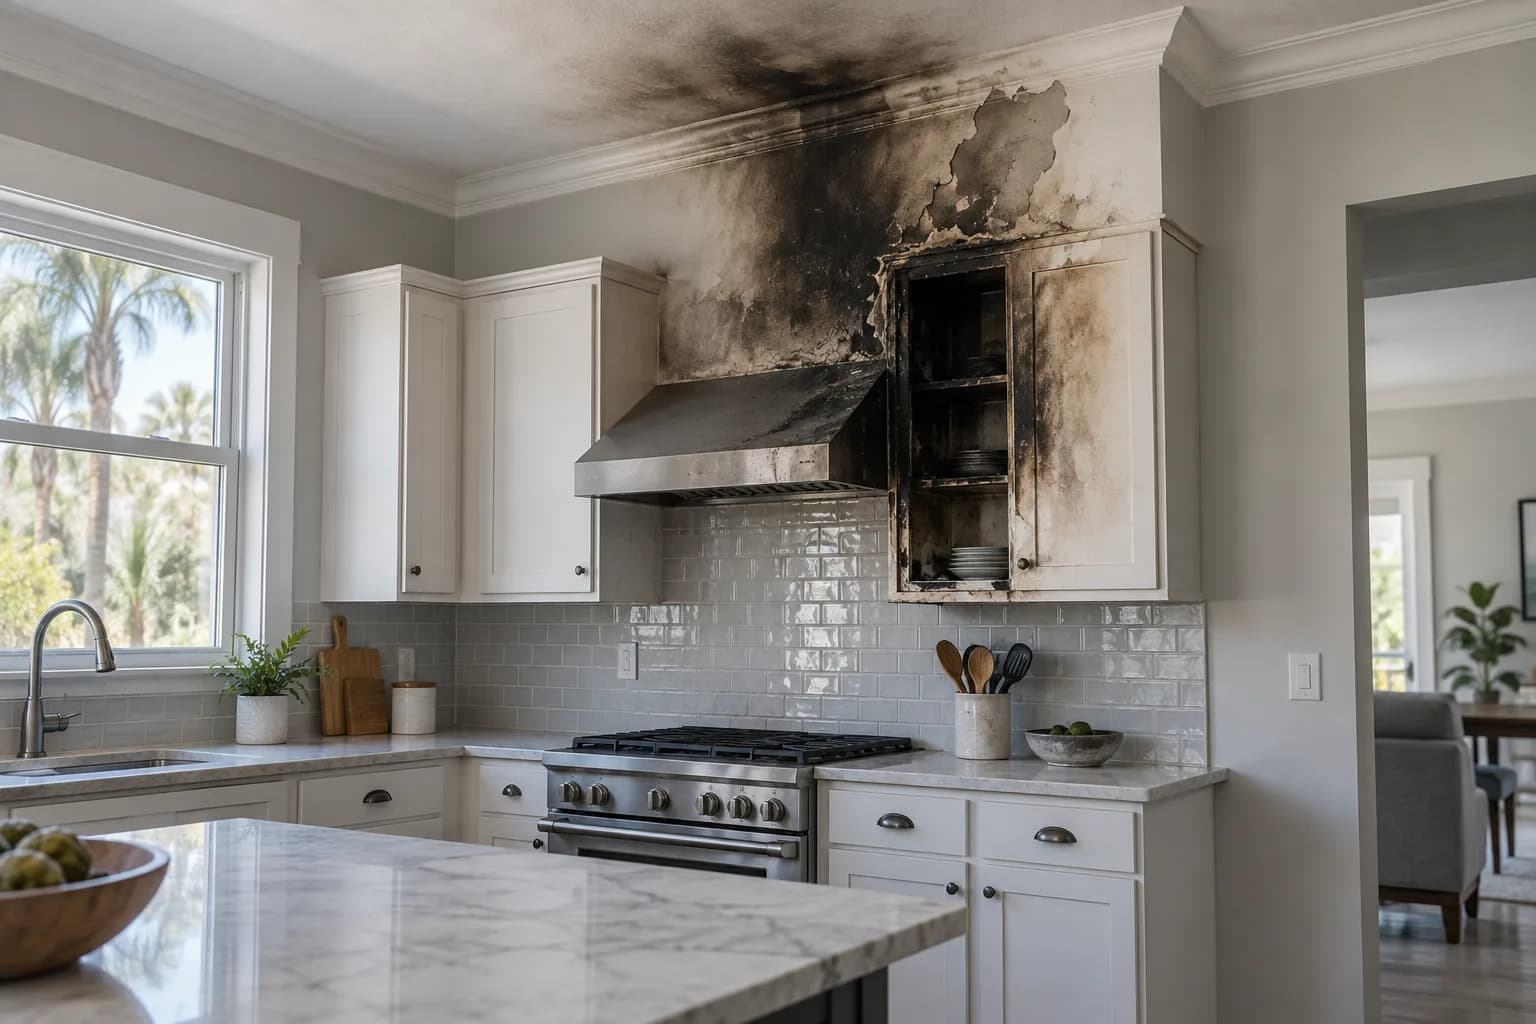
- Hidden damage found when walls, floors or ceilings are opened
- Repair costs that turn out higher than the insurer’s estimate
- Code-required work that was not in the original scope
- Damaged items that were missed in the first inventory
Reopened vs. supplemental
A reopened claim is a claim the insurer had closed and that is reopened at your request for additional costs for damage already disclosed. The difference matters for deadlines: notice of a new or reopened claim must be given within 1 year after the date of loss, while a supplemental claim must be noticed within 18 months after the date of loss.
What to send the insurer
A supplemental claim is easier to evaluate when it explains what changed:
- A written notice that refers to the original claim number
- Photos of the newly found damage, taken before it is covered up
- A detailed estimate or invoice for the additional work
- Reports from the contractor, plumber or engineer who found the damage
The insurer’s timeline
The 60-day rule in section 627.70131 also applies to supplemental claims: within 60 days after receiving notice, the insurer must pay or deny the claim or a portion of it, unless factors beyond its control prevent it. It must explain in writing the basis for a payment, denial or partial denial, and late payments generally accrue interest.
Tips during repairs
Ask your contractor to stop and photograph if they find unexpected damage, and tell the insurer before that area is closed again. Keep every invoice and change order. Do not wait until all repairs are finished if the 18-month mark is close. RicardoPA handles supplemental claims and can prepare the estimate and documentation.
Frequently asked questions
How long do I have to file a supplemental claim in Florida?
Notice of a supplemental claim must be given to the insurer within 18 months after the date of loss.
Can I file a supplemental claim after the insurer paid?
Yes, if you find additional damage from the same event or incur additional repair costs, within 18 months after the date of loss.
Does the insurer have to answer a supplemental claim within 60 days?
Yes. Within 60 days after receiving notice, the insurer must pay or deny the supplemental claim or a portion of it, unless factors beyond its control prevent it.
General information only, based on Florida law at the date shown. It is not legal advice, and initial guidance does not replace an evaluation by a licensed public adjuster.