Coverage basics
Water from a pipe and a $10,000 cap: what to document from day one
What to document after water from a pipe or an appliance damages your Florida home, when your policy limits that kind of water damage to $10,000.
By Ricardo Arevalo, Florida Public Adjuster · Published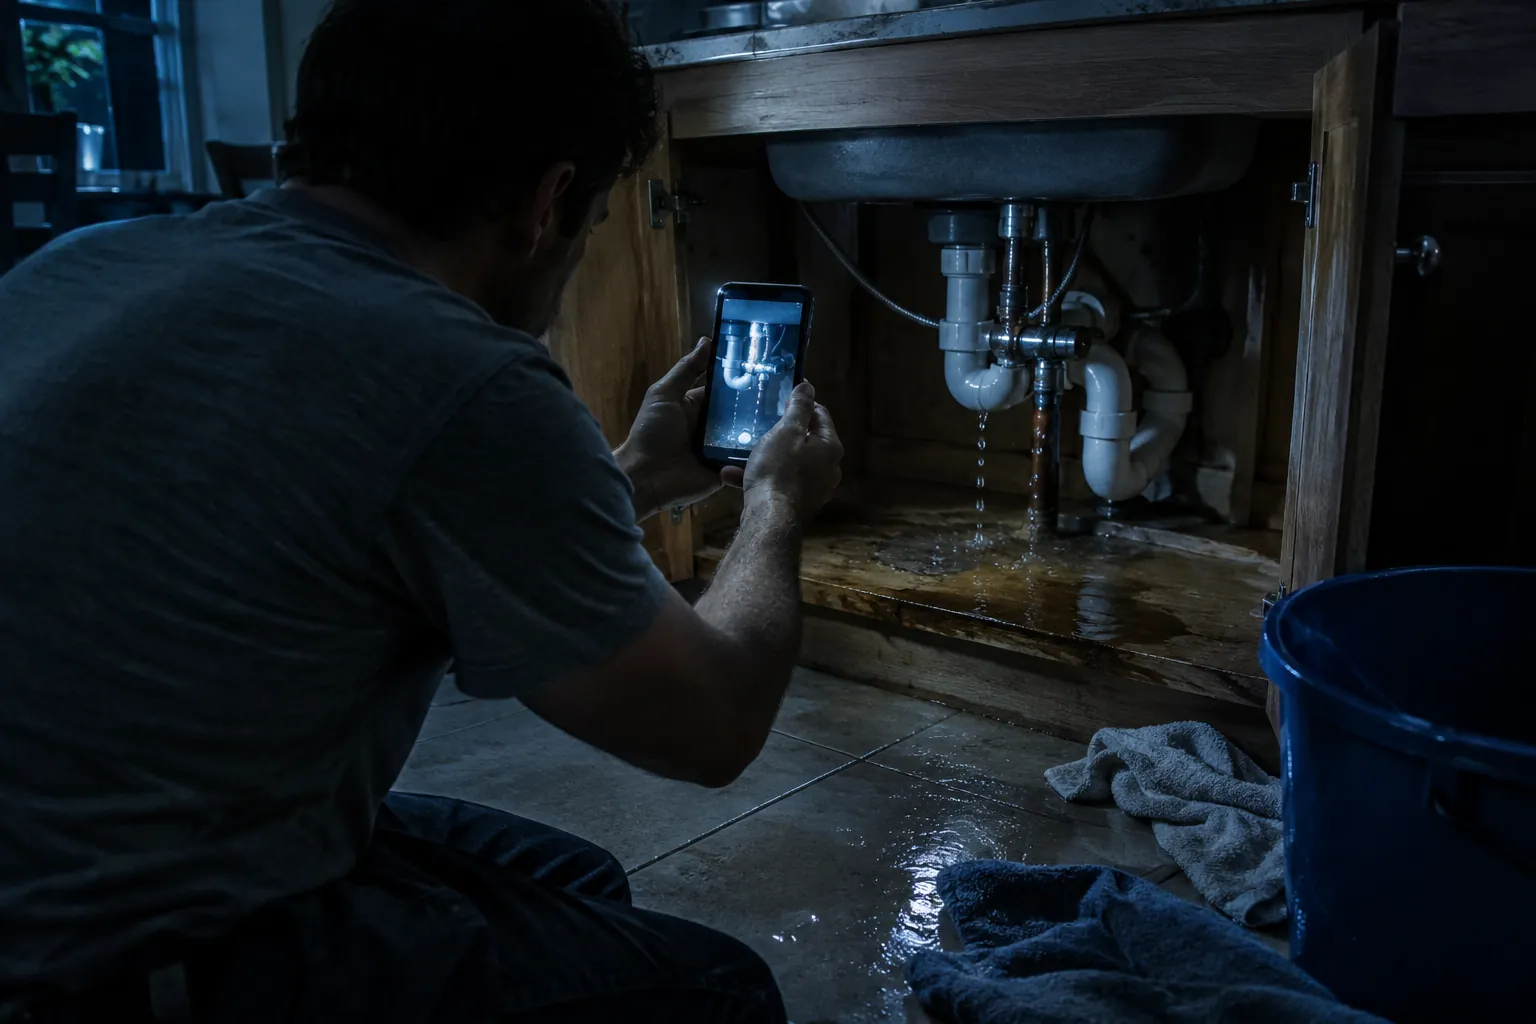
First, find out which limit applies
Before moving a single piece of furniture, look at the policy. The declarations page and the endorsements show whether there is a water damage limit, a separate deductible or a condition tied to the insurer’s repair program. At Citizens, for example, the $10,000 cap applies to those who choose not to use its contractor network, and emergency mitigation by another company is limited to $3,000.
The cause and the clock
The insurer will ask what failed and how long the water ran. It is not a minor question: policies commonly exclude constant or repeated seepage over 14 days or more. That is why it pays to photograph and film the source and the damage before anything is removed, keep the plumber’s report on what failed and when, and write down when the water was first noticed and when it was reported.
Drying is not repairing
Drying and water removal are often handled separately from permanent repairs, and some limits add the two together. Itemized invoices for each job, receipts for emergency repairs and the removed materials, or photos of them, help show what was done and why.
Notice, and questions in writing
Florida law requires notice of a new claim within 1 year after the date of loss, although the safer course is to report it as soon as possible. Questions to the insurer about repair or water removal programs, and about how the limits apply, are best asked in writing, with the answers kept. If more damage shows up later, Florida allows a supplemental claim within 18 months after the date of loss.
Frequently asked questions
Should I wait for the adjuster before drying my home?
Take reasonable steps to stop the water and prevent more damage, document everything first and keep the receipts. If your insurer offers an emergency water removal service, ask how using another company affects your limits.
What if the repairs cost more than $10,000?
That depends on your policy. A limit caps what the policy pays for that kind of loss, so check the limit, the conditions that trigger it and your deductible before repairs start, and ask the insurer in writing how they apply.
Can a public adjuster help with a limited water claim?
A public adjuster can document the damage, review the policy and present the claim for you. RicardoPA offers a free evaluation.
General information only, based on Florida law at the date shown. It is not legal advice, and initial guidance does not replace an evaluation by a licensed public adjuster.