Coverage basics
Can’t stay at home after a loss? How additional living expenses work
What loss of use or additional living expense coverage pays when a covered loss makes your Florida home unlivable, and which receipts to keep.
By Ricardo Arevalo, Florida Public Adjuster · Published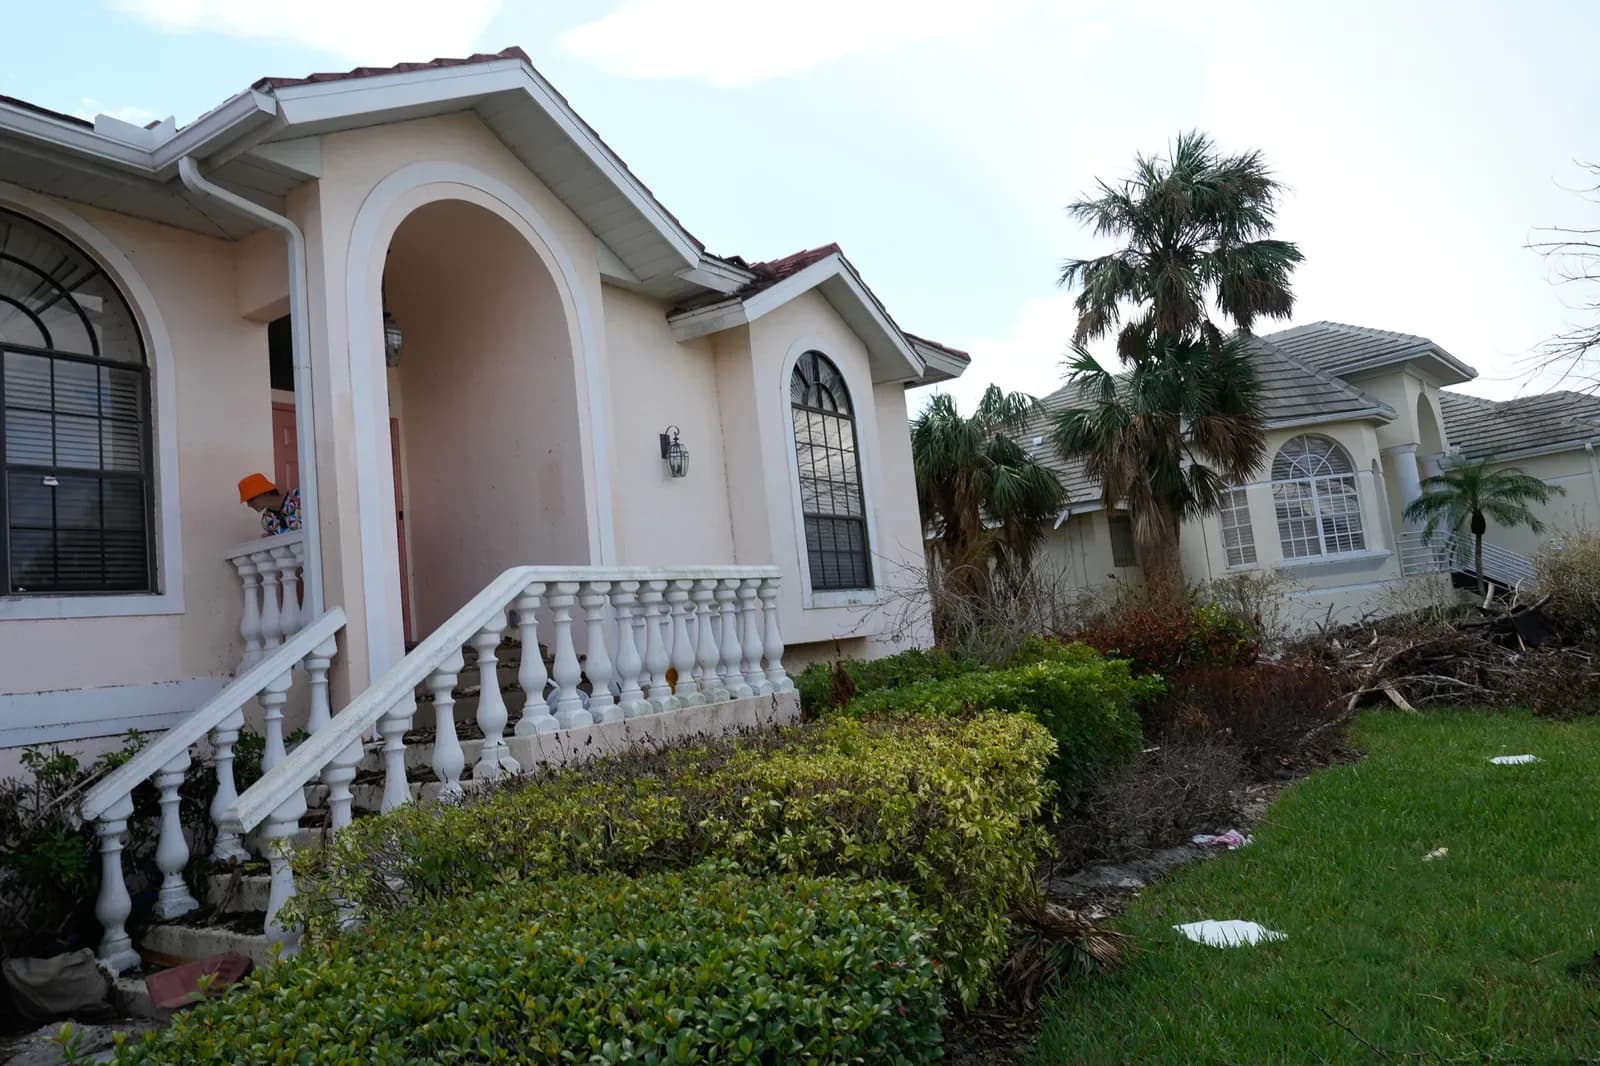
What the coverage is for
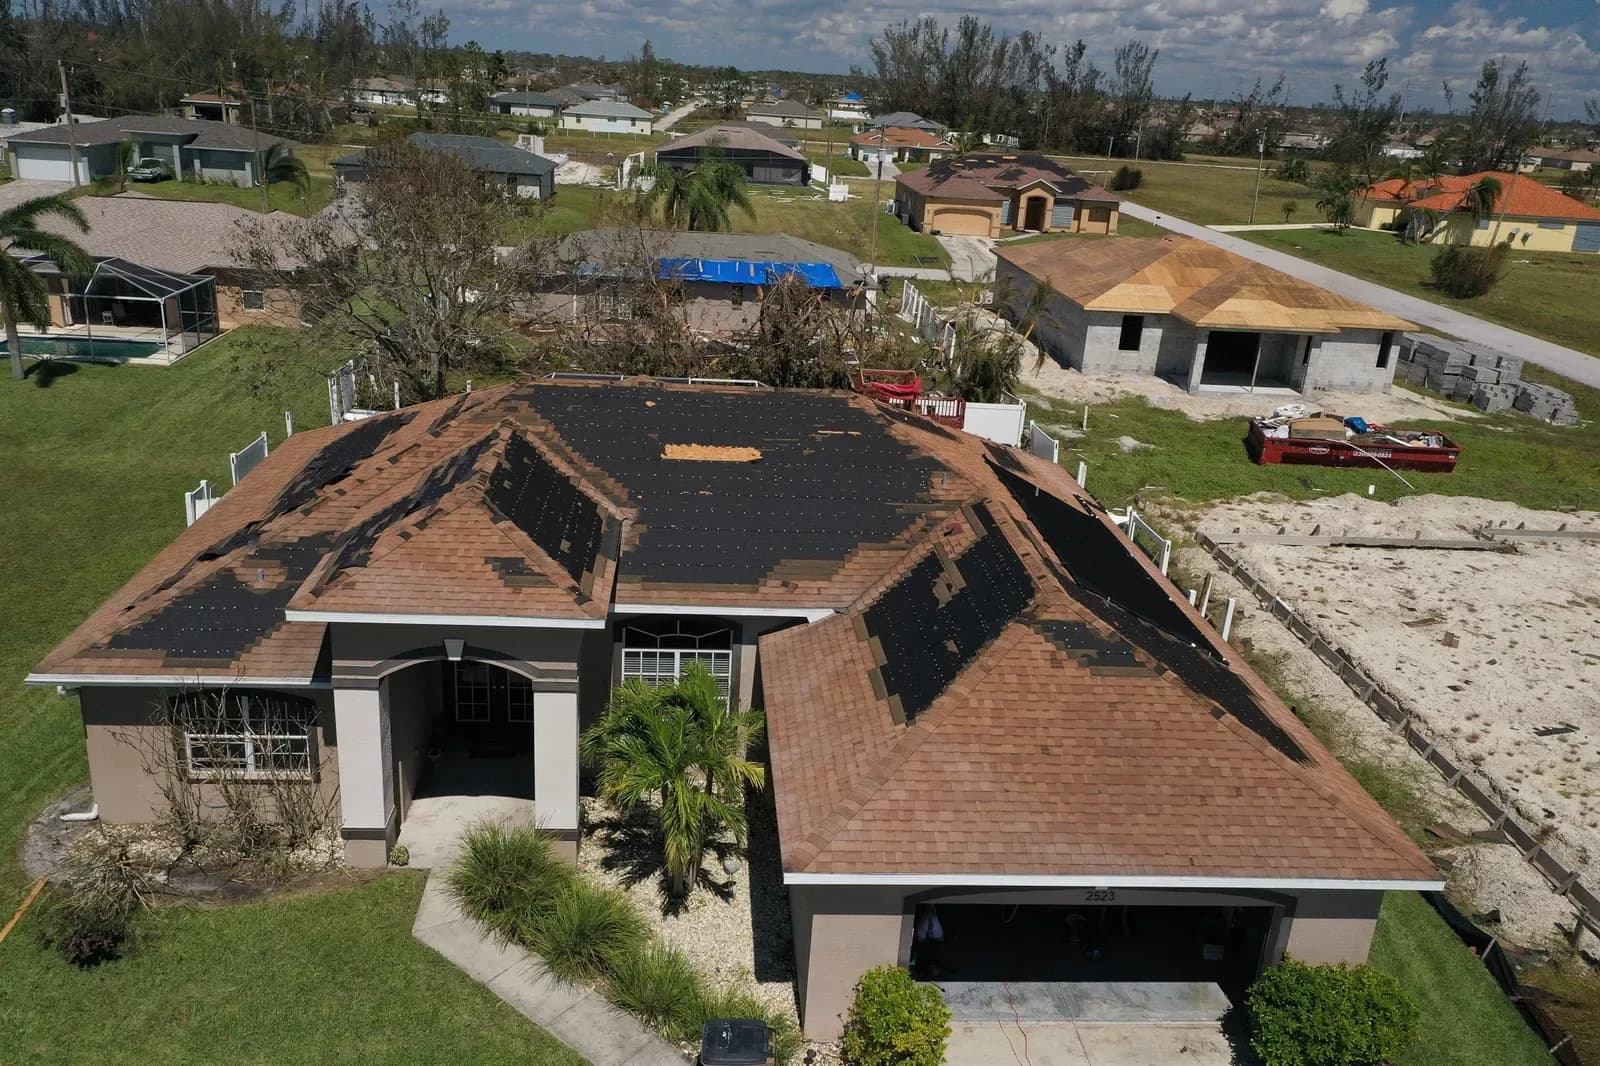
Most homeowners policies include loss of use coverage, often listed as Coverage D. Its additional living expense part pays the extra cost of living elsewhere when a covered loss makes your home unfit to live in. The Florida Department of Financial Services describes it as coverage for the “additional” expenses of an insured who must live elsewhere because of a covered loss.
“Additional” means the difference
The coverage usually pays the increase over your normal costs, not all of your expenses. Examples that often come up:
- A hotel or short-term rental while repairs are made
- Extra mileage or transportation because you are staying farther away
- Restaurant meals above what you normally spend on groceries
- Laundry, storage or pet boarding you would not otherwise pay
Your normal mortgage or rent usually continues as before and is not part of the claim.
Limits and time
The declarations page shows the loss of use limit, often a percentage of the dwelling limit or a set dollar amount. Policies usually pay for the shortest time reasonably needed to repair the home or for your household to settle elsewhere. Some policies also cover fair rental value when you rent part of the property to others, and loss of use when a civil authority prohibits access after a covered event.
Keep the receipts organized
Living expenses are easier to recover with a simple record:
- Every lodging, meal and transportation receipt, with dates
- A short comparison with your normal monthly costs before the loss
- Correspondence approving or questioning expenses
- Notes on why the home was unlivable: no power or water, unsafe areas, mold or repairs in progress
Ask early
Tell the insurer as soon as you have to leave the home and ask what it needs to approve expenses. Keep a running total so you can see how close you are to the limit. Loss of use is an often overlooked part of a claim; RicardoPA can review it with the rest of your claim during a free evaluation.
Frequently asked questions
Does homeowners insurance pay for a hotel after water damage?
If a covered loss makes the home unfit to live in, additional living expense coverage generally pays the extra cost of a hotel or rental, up to the policy limit and for the time reasonably needed.
Is loss of use paid if the damage is not covered?
Generally no. Loss of use follows a covered loss. If the underlying damage is excluded, the related living expenses usually are too.
Do condo owners have this coverage?
Unit owner (HO-6) policies commonly include loss of use as well. Check your declarations page for the limit.
General information only, based on Florida law at the date shown. It is not legal advice, and initial guidance does not replace an evaluation by a licensed public adjuster.